Stop-Loss Sizing: Position Sizing by Volatility Index (VIX) Market Volatility
Learn how to scale stop-losses and position sizes using market-wide volatility indexes like the VIX to protect capital during market dumps.
🔧 Interactive Utility Tool
Try the free, 100% secure client-side tool associated with this guide. No registration required.
Position Sizing by Volatility Index (VIX) Market Risk
Looking for a secure way to analyze and optimize your workflows? Here is a quick reference guide on the subject.
Position sizing models are risk-management calculations used to determine optimal capital allocations. By calculating metrics like ATR volatility, maximum drawdown, or the Sharpe and Sortino ratios, traders manage protection zones and limit trade losses.
When trading individual stocks or crypto, it's easy to focus solely on the asset's own chart. However, when market-wide panic spikes, historical correlations break down, and almost all risk assets drop together. To protect your equity curve during these periods of high systemic risk, professional managers scale their position sizes and stop-loss boundaries based on broad volatility indexes like the CBOE Volatility Index (VIX).
In this guide, we'll explain what the VIX measures, detail volatility-scaling rules, and map risk limits.
Product-Led CTA: Managing risk manually is slow and leads to trading errors. Use our free, real-time Position Size Calculator to quickly model share counts and risk targets.
📐 Understanding the VIX (The Fear Gauge)
The VIX measures the stock market's expectation of 30-day volatility implied by S&P 500 options pricing:
⚡ Quick Action: Use the Online Tool
This guide pairs with our free, 100% secure client-side utility tool. Process your files or text instantly in-browser.
- VIX < 15: Indicates low systemic risk and high complacency. Ideal environment for standard swing trading.
- VIX 20 - 30: Indicates elevated market concern. Volatility is rising; price pullbacks are sharper.
- VIX > 30: Indicates extreme panic or capitulation. Assets correlate to 1.0, and price swings are massive.
📊 Volatility Curves Reference
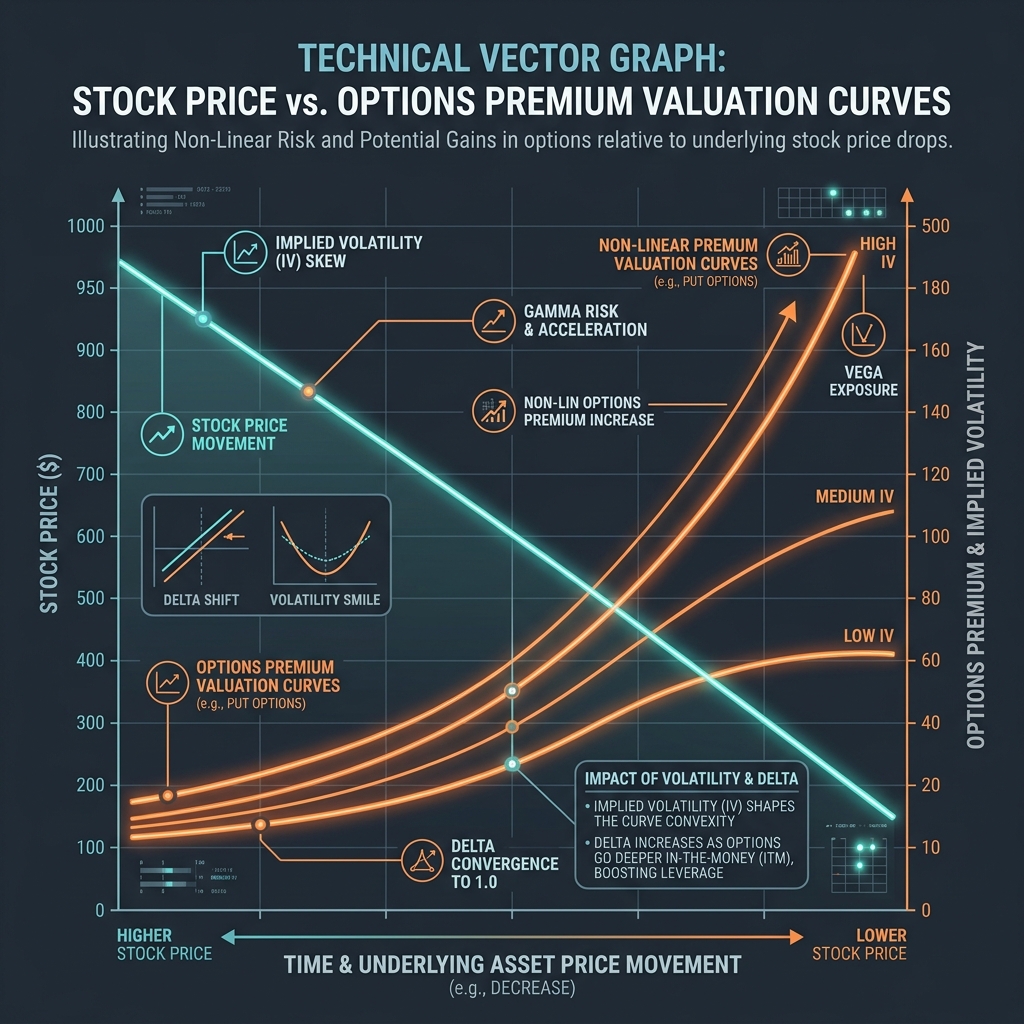
During market spikes, options premium delta decay curves shift rapidly, increasing risk for options buyers. The chart below illustrates how option premium delta decay curves behave across different implied volatility (IV) conditions:
🔍 The Volatility-Scaling Sizing Model
To protect capital, scale your risk per trade ($R_{\text{trade}}$) downward as the VIX increases:
| VIX Level | Systemic Risk | Stop-Loss Policy | Maximum Risk Per Trade |
|---|---|---|---|
| Below 15 | Complacent | Standard ATR Stops (2.0x ATR) | 2.0% of Account Capital |
| 15 to 25 | Elevated | Moderate Stops (2.5x ATR) | 1.0% of Account Capital |
| Above 25 | Extreme Panic | Tighten Stops & Halve Allocations | 0.5% of Account Capital |
This model ensures that when the overall market becomes unpredictable, you automatically trade smaller sizes. Even if a series of stop-outs occurs during a panic, your portfolio drawdown remains controlled.
🛠️ Portfolio Sizing Utilities
To structure your portfolio risk: * Structure Allocation Limits: Read Position Sizing with the Kelly Criterion to optimize wins. * Select Volatility Stops: Read Stop-Loss Multipliers Sizing Guide. * Compute Sizing Instantly: Use our browser-based Position Size Calculator to quickly model share counts and risk targets.
Join the Urbandigistore Hub
Subscribe to receive premium developer cheat sheets, advanced conversion techniques, and campaign optimization checklists. Zero spam, unsubscribe anytime.
🚀 Launch Interactive Tool
Ready to test this directly? Open the secure web tool in a new sandbox tab.